CfPA Initiatives & Milestones Timeline (2016 - Present)
 Crowdfunding Professional Association (CfPA)
Last updated: September 27, 2026
The Crowdfunding Professional Association (CfPA) is a 501(c)(6) nonprofit trade association established shortly after the signing of the JOBS Act on April 5, 2012, dedicated to fostering the growth of the Regulated Investment Crowdfunding economy and supporting the SEC and FINRA in rulemaking, education, and investor protection. Below is a running timeline of CfPA initiatives, advocacy, events, and milestones since Regulation Crowdfunding went live in 2016, in reverse chronological order. (For the association's founding era, see the 2012 - 2016 summary at the end of this page.)
2026 Executive Leadership
Brian Belley, President · Jenny Kassan, Chair
Executive Committee: Jenny Kassan, Brian Belley, Brian Christie, Devin Thorpe, Scott McIntyre, Andrew Stephenson, Jason Fishman
Milestones & Major Activities
Oct 20-21, 2026 (upcoming) -- Third Annual Regulated Investment Crowdfunding Summit, Washington, DC. "Investor Outcomes and Crowdfunding in an...more
2026 - Speakers and Sponsors
 2026 CfPA Regulated Investment Crowdfunding Summit
Speakers & Sponsors
Meet the leaders joining this year's Summit and the organizations supporting the regulated investment crowdfunding ecosystem.
National Union Building • Washington, DC
This companion to the detailed Summit agenda provides background on the speakers participating in the program and the organizations helping make the 2026 CfPA Regulated Investment Crowdfunding Summit possible.
Summit Speakers
Leaders from government, finance, law, technology, entrepreneurship and the investment crowdfunding ecosystem.
Vincent Bowen, Founder @ Mavin (social platform where members will share revenues), BLM5280 Core Leader. Former Morgan Stanley, Goldman Sachs, and Robertson Stephens investment banker, Bundesbank Fellow.
Presumptive Parity: A New Principle for America's Patchwork of Exempt Capital Markets
The Securities and Exchange Commission (SEC) proposed Regulation Crypto Assets on August 18. Comments are due October 20.
Nothing is final. It is a proposing release, open for comment, and the rules may change before adoption.
Law360 published my argument about it on August 25, under the headline, "A Guiding Principle For The SEC On Exempt Capital Markets." What follows is the same doctrine with the parts I could not fit there.
The doctrine, in four sentences:
Presumptive Parity means that when the SEC creates or materially changes an exempt capital-raising pathway, it should compare that pathway with similarly situated existing pathways. Comparable opportunities and burdens should be the starting assumption unless meaningful differences justify different treatment. The burden of identifying a meaningful difference falls on whoever defends the disparity, and novelty alone is not such a difference. Where no justification exists, the Commission should move toward parity to the exte...more
The raise is the claim event
Most Regulation Crowdfunding (Reg CF) and Regulation A issuers I talk to put Directors and Officers (D&O) on the closing checklist.
That treats the policy like a trophy for getting the money in. It is not.
The 1933/1934 Act exclusion on a standard private-company form was written for IPOs. A Form C, the SEC crowdfunding filing, is still a securities offering. A normal private policy treats it like a public offering and excludes it.
Retail investors under Reg CF and Reg A read what you filed. They did not sit in your office. If something in that filing is wrong, the people who signed it get named.
Side A, the part that pays a director when the company cannot, only helps if the form actually responds to a JOBS Act offering.
This is not an argument for a bigger tower. It is an argument for binding before go-live, on paper that does not dump the listing.
Question for issuers and portals: are you binding a raise form before the offering goes live, or is D&O still sitting behind the ...more
CfPA Introduces Industry Best Practice for Reg CF Annual Reporting
The Crowdfunding Professional Association (CfPA) has introduced a new industry Best Practice designed to help companies raising capital under Regulation Crowdfunding better understand their ongoing SEC reporting responsibilities.
Companies that sell securities through Regulation Crowdfunding are generally required to file an annual report on Form C-AR within 120 days of the end of their fiscal year and post the report on their website. Annual reporting continues until the company qualifies to terminate its reporting obligation under SEC rules and files Form C-TR.
While compliance with these requirements remains the responsibility of the company—not the funding portal or broker-dealer that facilitated the offering—CfPA believes the industry can help reduce inadvertent noncompliance by making these obligations clear before an offering begins.
Under the new Best Practice, CfPA encourages Reg CF intermediaries to consider incorporating an acknowledgment of ongoing reporting responsibilitie...more
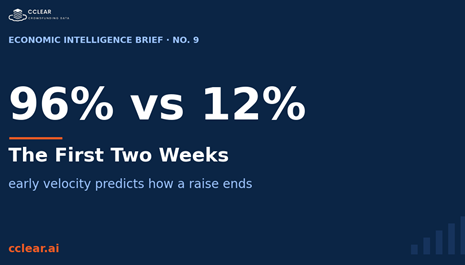
The first 14 days of your offering might be the most important ...
A startup's first 14 days predict how its entire raise ends. We can prove it.
We tested it out of sample across 6,300+ offerings. The fastest-starting quartile finished strong 96% of the time. The slowest quartile? 12%.
The signal holds up year after year (AUC 0.88 to 0.92). Momentum isn't a vibe. It's measurable, and it's predictive.
To be clear, this predicts the raise, not the investment return.
A question for the operators: if the first two weeks are this decisive, is a slow-starting campaign already finished, or can a raise still be saved once it stalls?
Comment "CCLEAR" and I'll send you the full brief.
...more
CfPA Member Resource Center | Your Membership Benefits & Resources
Welcome to the CfPA Member Resource Center!
Your central hub for the exclusive benefits, opportunities, and resources available through your Crowdfunding Professional Association membership. Whether you're looking to expand your professional network, increase your visibility in the industry, develop your expertise, or make the most of your membership, this page is here to help. As new member benefits become available, this resource will be updated, so we encourage you to bookmark it and check back regularly.
Why Become a CfPA Member?
Membership in the Crowdfunding Professional Association is more than joining an organization; it's becoming part of a community dedicated to advancing regulated investment crowdfunding through education, advocacy, collaboration, and professional development. As a member, you'll gain access to exclusive opportunities designed to help you grow your network, strengthen your expertise, raise your professional profile, and actively shape the future of the indus...more
Silicon Valley's grip on startup capital is slipping.
In crowdfunding, the data already shows it. 64% of funded Reg CF capital now goes to companies outside California, New York, and Massachusetts, up from 47% in 2016. The top five states' share fell from 74% to 52%. California alone went from 44% to 26%.
And the per-resident leaders aren't who you'd guess: Wyoming, Nevada, Utah, Colorado. Take away the gatekeepers and the map of where innovation gets funded looks nothing like the venture map.
A real question: is capital actually decentralizing, or is crowdfunding just reaching the places venture was never going to fund anyway? Curious which way people see it.
Comment "CCLEAR" and I'll send you the full brief.
...more